India Rewind October 2026
2 min read
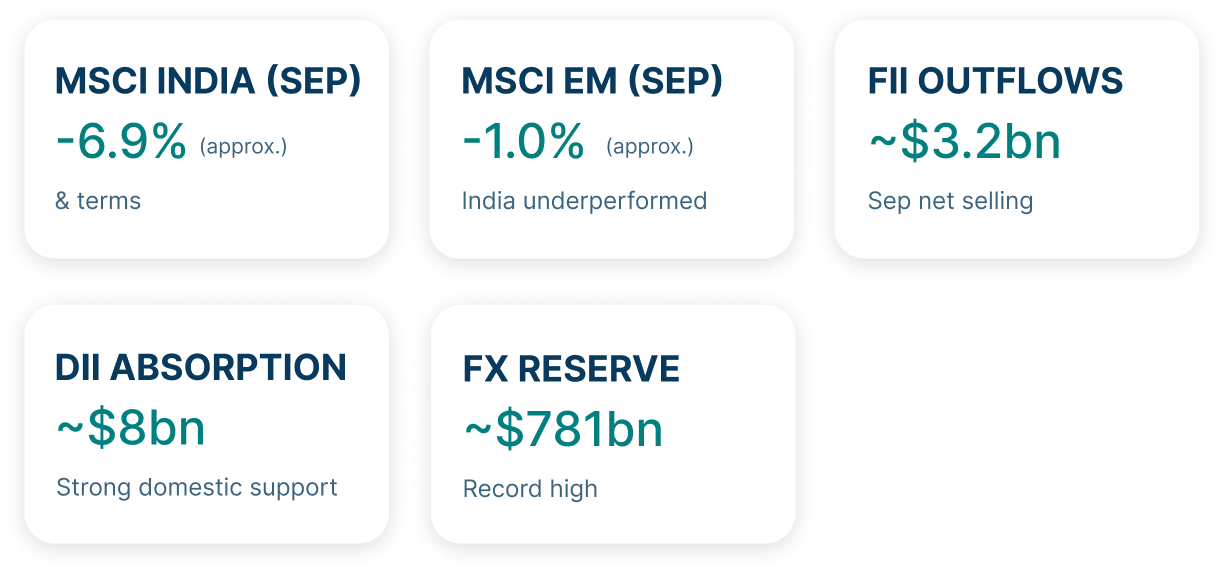
Markets: A Reversal Driven by External Conditions
Domestic Demand: Resilience Intact
Oil: The Swing Factor
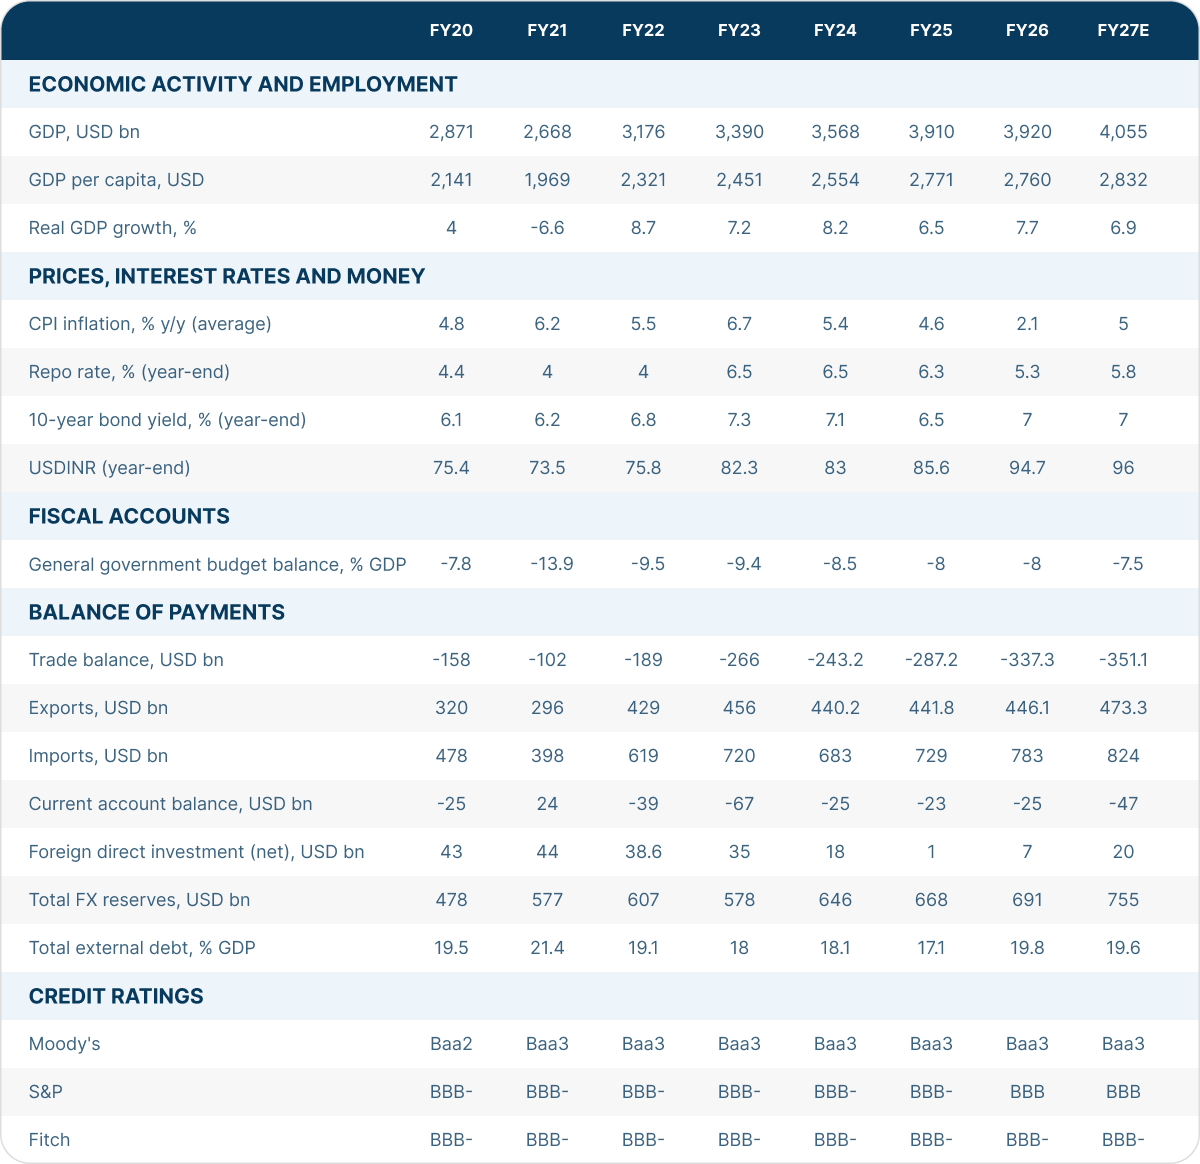
Valuations & What to Watch
Authors
Jay Kothari
Executive Director, Lead Investment Strategist

Info Source
Elara Capital, Nuvama, Morgan Stanley Research, MOFSL, Avendus Spark Research, UBS, Kotak Securities. Data as of September 2026. MXASJ – MSCI Asia Ex-Japan, FPI – Foreign Portfolio Investor, DII – Domestic Institutional Investor, RBI – Reserve Bank of India, FY – Financial Year, CY – Calendar Year; YoY is Year over Year, YTD – Year to date, EM – Emerging Markets, DM – Developed Markets, FTA - Free Trade Agreement. Past performance should not be taken as an indication or guarantee of future performance
Investment Risk Warning
Investments involve risk. The value of investments and any income arising from them may go down as well as up and investors may not receive back the full amount originally invested. Capital is at risk. Investments in international markets, emerging markets and specialist investment strategies may be subject to higher volatility and additional risks. Prospective investors should carefully consider the relevant offering documents and seek independent professional advice before making any investment decision. Past performance is not a reliable indicator of future results. Forward-looking statements, forecasts and projections are not guarantees of future performance. Adapted from DSP website compliance disclosures.
Risks
Actual results may differ materially from those suggested by the forward looking statements due to risk or uncertainties associated with our expectations respect to, but not limited to, exposure to market risks, general economic and political conditions in India and other countries globally, which have an impact on our services and / or investments, the monetary and interest policies of India, inflation, deflation, unanticipated turbulence in interest rates, foreign exchange rates, equity prices or other rates or prices etc. All figures and other data given in this document are dated and the same may or may not be relevant in future and the same should not be considered as solicitation / recommendation / guarantee of future investments by the AMC or its affiliates. This communication contains information which refers to the past as well as information on future performance. Neither past performance nor forecasts are a reliable indicator of future performance. This information and associated materials have been provided to you at your express request, and for your exclusive use. This information is not intended for distribution to, or use by, any person or entity in any jurisdiction or country where such distribution would be unlawful under the securities laws of such jurisdiction or country. Any distribution, by whatever means, of this information and related material to persons other than those referred to above is strictly prohibited. Distribution of this communication may be restricted in certain jurisdictions. Any product(s) mentioned within this communication (i) may not be registered for distribution in your jurisdiction, and (ii) may only be available to professional or otherwise qualified investors or entities. The information is for general guidance only, and it is the responsibility of any person or persons in possession of this material to inform themselves of, and to observe any such restrictions, all applicable laws and regulations of any relevant jurisdiction, including of any applicable legal requirements, exchange control regulations and taxes in the countries of their respective citizenship, residence or domicile. Past performance may or may not be sustained in the future. There is no assurance of any capital protection / capital guarantee to the investors. The sector(s) / stock(s) / issuer(s) mentioned in this document do not constitute any recommendation of the same. Investors are advised to consult their own legal, tax and financial advisors to determine possible tax, legal and other financial implication or consequence of investing into the investment strategies.
Privacy preferences
DSP International (UK) Limited uses cookies
We use strictly necessary cookies to keep this Website secure and working properly. With your consent, we'd also like to use analytics cookies to understand how the site is used, and advertising cookies to show more relevant content. Read our Cookie Policy for full details.