Structural, Sustainable Growth
7.3%
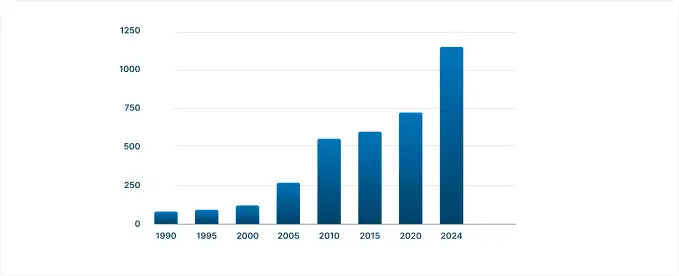
FY26 GDP growth forecast Highest among top X economies by size
Source: IMF
December capped a resilient yet uneven 2025 for Indian markets. Early in the year, emerging markets outperformed amid mixed global signals, but this divergence proved short-lived. By mid-year, uncertainty stemming from Trump-era tariff threats and shifting timelines around the US–India trade deal weighed on foreign flows, despite strong domestic fundamentals and central bank easing. Over the year, markets navigated these cross-currents, with MSCI India up ~3%. However, it lagged MSCI EM’s broader ~31% and MSCI DM’s ~19% gains, which were driven largely by AI, Technology, and semiconductor-led rallies that dominated global risk appetite.
December capped a resilient yet uneven 2025 for Indian markets. Early in the year, emerging markets outperformed amid mixed global signals, but this divergence proved short-lived. By mid-year, uncertainty stemming from Trump-era tariff threats and shifting timelines around the US–India trade deal weighed on foreign flows, despite strong domestic fundamentals and central bank easing. Over the year, markets navigated these cross-currents, with MSCI India up ~3%. However, it lagged MSCI EM’s broader ~31% and MSCI DM’s ~19% gains, which were driven largely by AI, Technology, and semiconductor-led rallies that dominated global risk appetite.
December capped a resilient yet uneven 2025 for Indian markets. Early in the year, emerging markets outperformed amid mixed global signals, but this divergence proved short-lived. By mid-year, uncertainty stemming from Trump-era tariff threats and shifting timelines around the US–India trade deal weighed on foreign flows, despite strong domestic fundamentals and central bank easing. Over the year, markets navigated these cross-currents, with MSCI India up ~3%. However, it lagged MSCI EM’s broader ~31% and MSCI DM’s ~19% gains, which were driven largely by AI, Technology, and semiconductor-led rallies that dominated global risk appetite.
December capped a resilient yet uneven 2025 for Indian markets. Early in the year, emerging markets outperformed amid mixed global signals, but this divergence proved short-lived. By mid-year, uncertainty stemming from Trump-era tariff threats and shifting timelines around the US–India trade deal weighed on foreign flows, despite strong domestic fundamentals and central bank easing. Over the year, markets navigated these cross-currents, with MSCI India up ~3%. However, it lagged MSCI EM’s broader ~31% and MSCI DM’s ~19% gains, which were driven largely by AI, Technology, and semiconductor-led rallies that dominated global risk appetite.

Investor-first mindset focused on compounding investor value over decades.

Values-driven, principled, and transparent about our process and the risk-reward of investing in a dynamic market like India.
Policy reforms during the year reinforced this macro stability. Income-tax cuts and GST 2.0 rationalisation supported household affordability and facilitated price pass-through, strengthening the disinflationary impulse. Accounting for favourable base effects alongside these reforms, headline CPI eased to below 1% by November, while core inflation moderated to ~4.3%. Complementing this backdrop, liquidity conditions remained comfortable in December, supported by active RBI operations including open-market bond purchases and USD/INR swap auctions, helping preserve money-market stability and reinforce monetary policy transmission. For the broader market during 2025, earnings through the year pointed to a selective recovery.
Policy reforms during the year reinforced this macro stability. Income-tax cuts and GST 2.0 rationalisation supported household affordability and facilitated price pass-through, strengthening the disinflationary impulse. Accounting for favourable base effects alongside these reforms, headline CPI eased to below 1% by November, while core inflation moderated to ~4.3%. Complementing this backdrop, liquidity conditions remained comfortable in December, supported by active RBI operations including open-market bond purchases and USD/INR swap auctions, helping preserve money-market stability and reinforce monetary policy transmission. For the broader market during 2025, earnings through the year pointed to a selective recovery.
President - DSP Group and DSP Investments

MD & CEO - DSP Mutual Fund
FY26 GDP growth forecast Highest among top X economies by size
Source: IMF
Of MSCI ACWI Under-represented despite contributing 4% of global GDP
Source: IMF