Structural, Sustainable Growth
7.3%
FY26 GDP growth forecast Highest among top X economies by size
Source: IMF
December capped a resilient yet uneven 2025 for Indian markets. Early in the year, emerging markets outperformed amid mixed global signals, but this divergence proved short-lived. By mid-year, uncertainty stemming from Trump-era tariff threats and shifting timelines around the US–India trade deal weighed on foreign flows, despite strong domestic fundamentals and central bank easing. Over the year, markets navigated these cross-currents, with MSCI India up ~3%. However, it lagged MSCI EM’s broader ~31% and MSCI DM’s ~19% gains, which were driven largely by AI, Technology, and semiconductor-led rallies that dominated global risk appetite.
On the currency front, the rupee depreciated ~5% YTD, making it one of the weakest major EM currency in 2025 excluding inflation outliers, an outcome uncharacteristic of India’s historical EM positioning. While the RBI has reiterated that it does not defend any specific exchange-rate level, it moved to contain disorderly volatility through calibrated intervention. Measures included ~US$33.4bn of open-market bond purchases and ~US$15bn in three-year USD/INR buy-sell swaps, helping inject liquidity, rebuild reserves synthetically, and preserve policy flexibility during periods of seasonal tightness. Against this backdrop, FPI flows emerged as a defining feature of the year. Cumulative CY2025 FPI net outflows reached ~US$19bn, reflecting pressure from a firm dollar, rise in yields, and prolonged uncertainty around trade negotiations. As global capital gravitated toward AI and technology-heavy markets, conviction toward broader EM allocations weakened, with India also seeing selective de-risking amid extended India–US trade timelines.
December capped a resilient yet uneven 2025 for Indian markets. Early in the year, emerging markets outperformed amid mixed global signals, but this divergence proved short-lived. By mid-year, uncertainty stemming from Trump-era tariff threats and shifting timelines around the US–India trade deal weighed on foreign flows, despite strong domestic fundamentals and central bank easing. Over the year, markets navigated these cross-currents, with MSCI India up ~3%. However, it lagged MSCI EM’s broader ~31% and MSCI DM’s ~19% gains, which were driven largely by AI, Technology, and semiconductor-led rallies that dominated global risk appetite.
On the currency front, the rupee depreciated ~5% YTD, making it one of the weakest major EM currency in 2025 excluding inflation outliers, an outcome uncharacteristic of India’s historical EM positioning. While the RBI has reiterated that it does not defend any specific exchange-rate level, it moved to contain disorderly volatility through calibrated intervention. Measures included ~US$33.4bn of open-market bond purchases and ~US$15bn in three-year USD/INR buy-sell swaps, helping inject liquidity, rebuild reserves synthetically, and preserve policy flexibility during periods of seasonal tightness. Against this backdrop, FPI flows emerged as a defining feature of the year. Cumulative CY2025 FPI net outflows reached ~US$19bn, reflecting pressure from a firm dollar, rise in yields, and prolonged uncertainty around trade negotiations. As global capital gravitated toward AI and technology-heavy markets, conviction toward broader EM allocations weakened, with India also seeing selective de-risking amid extended India–US trade timelines.

Investor-first mindset focused on compounding investor value over decades.

Values-driven, principled, and transparent about our process and the risk-reward of investing in a dynamic market like India.
Policy reforms during the year reinforced this macro stability. Income-tax cuts and GST 2.0 rationalisation supported household affordability and facilitated price pass-through, strengthening the disinflationary impulse. Accounting for favourable base effects alongside these reforms, headline CPI eased to below 1% by November, while core inflation moderated to ~4.3%. Complementing this backdrop, liquidity conditions remained comfortable in December, supported by active RBI operations including open-market bond purchases and USD/INR swap auctions, helping preserve money-market stability and reinforce monetary policy transmission. For the broader market during 2025, earnings through the year pointed to a selective recovery.
Policy reforms during the year reinforced this macro stability. Income-tax cuts and GST 2.0 rationalisation supported household affordability and facilitated price pass-through, strengthening the disinflationary impulse. Accounting for favourable base effects alongside these reforms, headline CPI eased to below 1% by November, while core inflation moderated to ~4.3%. Complementing this backdrop, liquidity conditions remained comfortable in December, supported by active RBI operations including open-market bond purchases and USD/INR swap auctions, helping preserve money-market stability and reinforce monetary policy transmission. For the broader market during 2025, earnings through the year pointed to a selective recovery.
President - DSP Group and DSP Investments

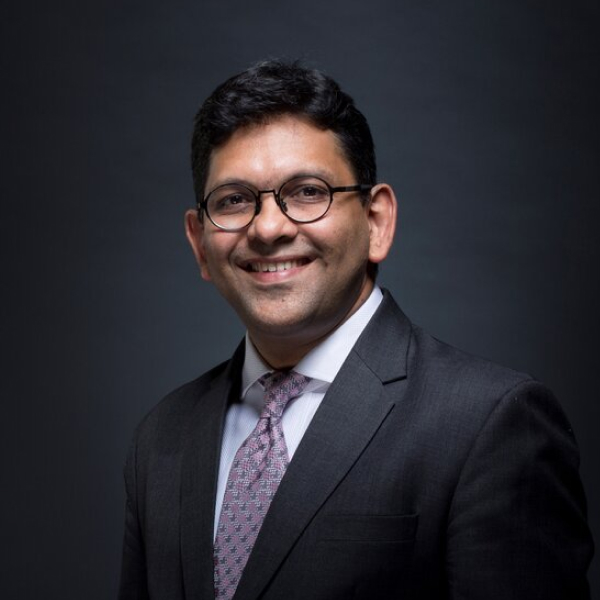
MD & CEO - DSP Mutual Fund
FY26 GDP growth forecast Highest among top X economies by size
Source: IMF
Of MSCI ACWI Under-represented despite contributing 4% of global GDP
Source: IMF